Firewise Communities & Home Insurance in Nevada Tahoe
Nevada Tahoe Wildfire & Insurance Guide
Firewise Communities & Home Insurance in Nevada Tahoe: What California, Washington, and Other High-Tax State Buyers Should Know
Moving to the no-income-tax side of Lake Tahoe? Before you write an offer, there is another important number to understand: your home insurance cost and how wildfire preparedness may affect the property.
Nevada's tax environment is an important reason buyers consider Incline Village, Glenbrook, Zephyr Cove, and other Nevada-side Lake Tahoe communities.
But for a mountain property, taxes are only part of the carrying-cost picture.
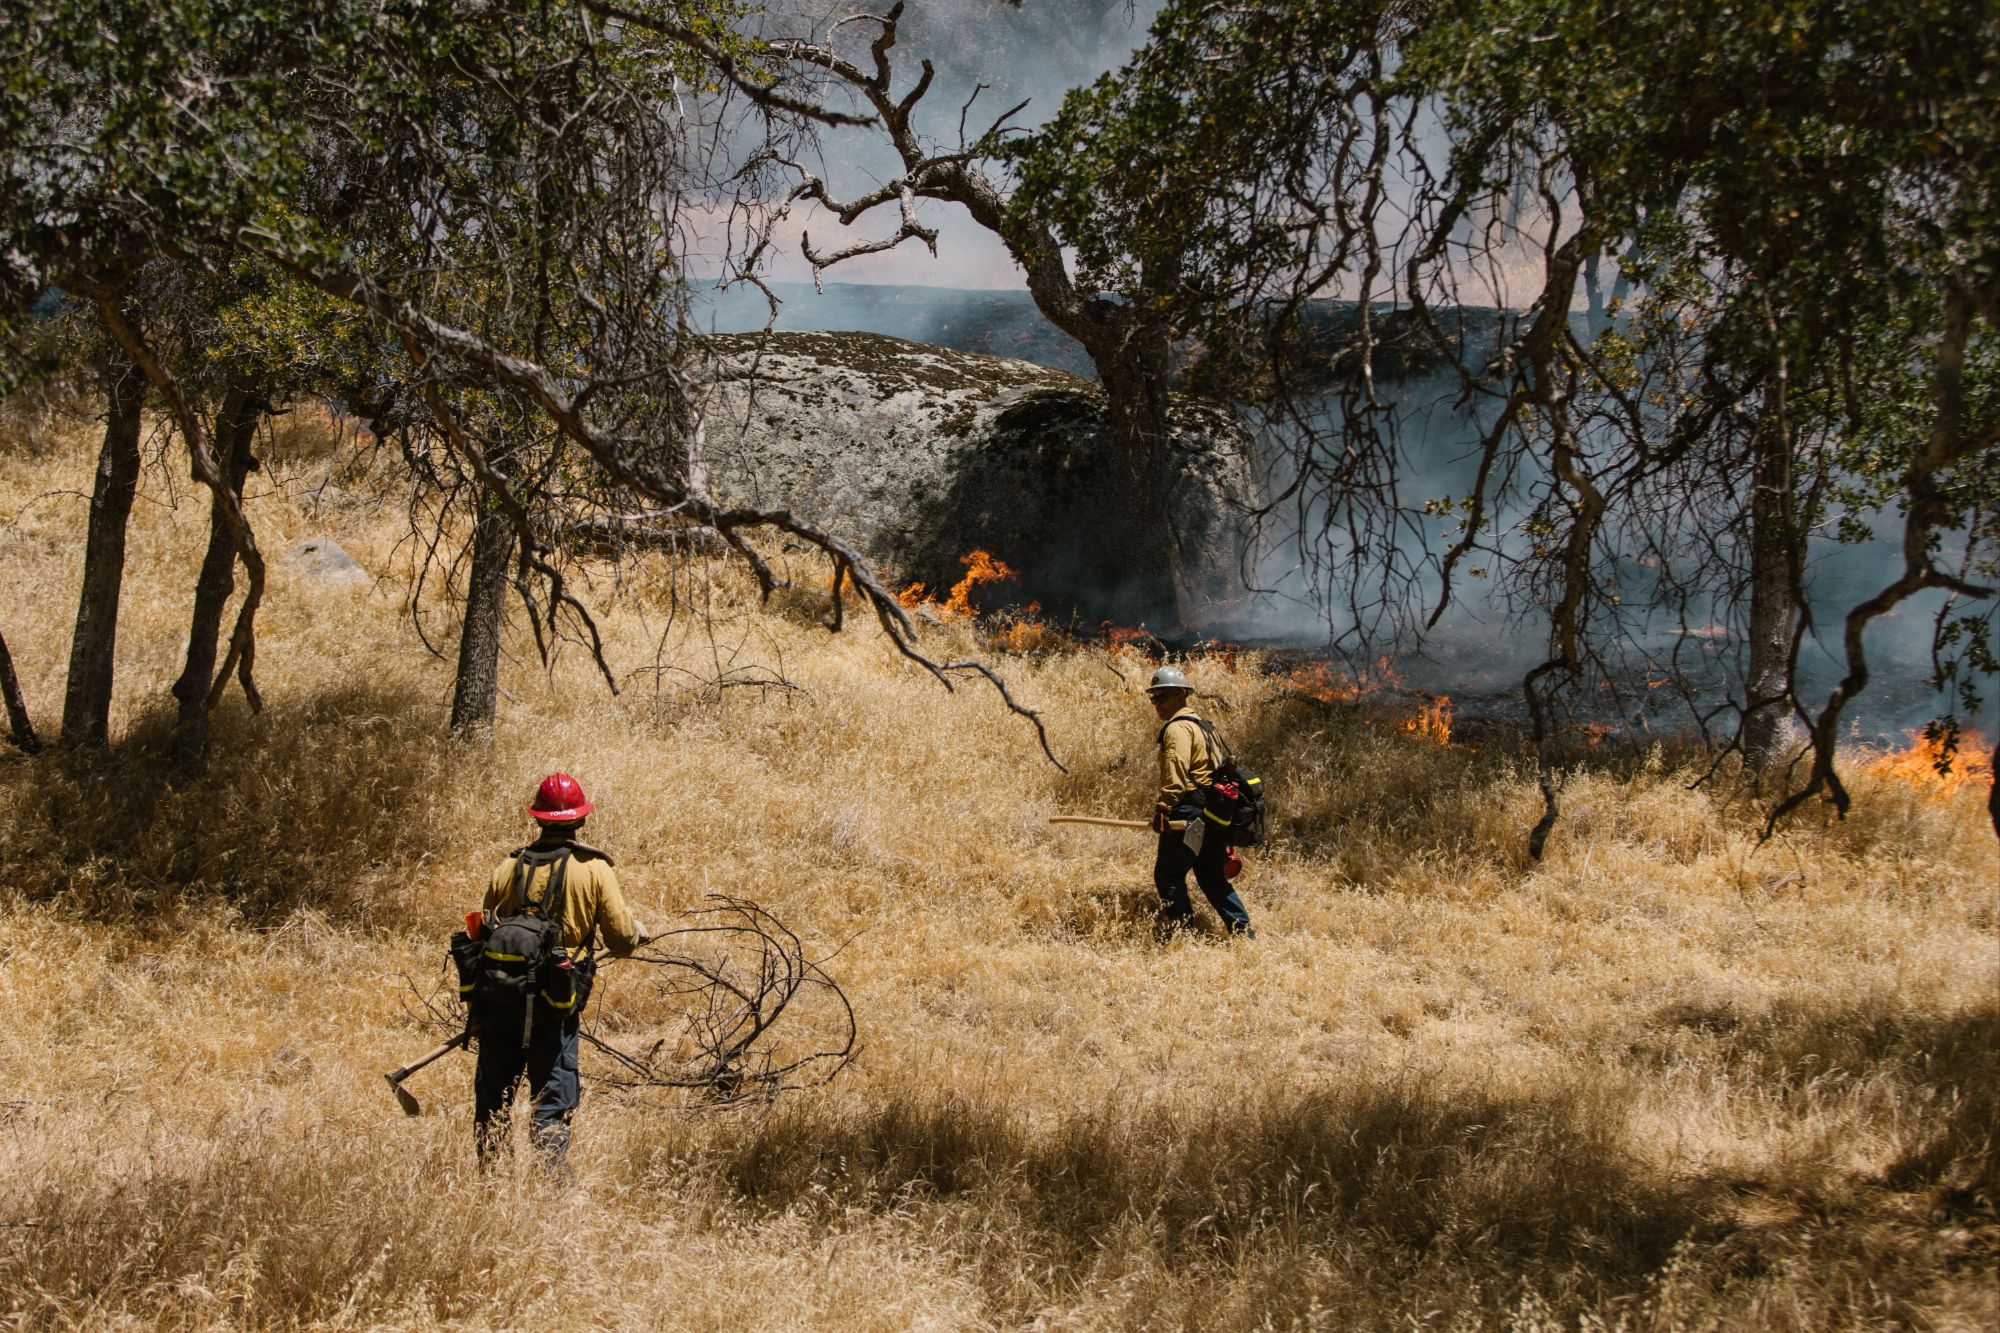
Before removing contingencies, buyers should also understand wildfire exposure, defensible space, the property's insurance options, and whether the surrounding neighborhood participates in organized wildfire-preparedness programs such as Firewise USA®.
What Is a Firewise USA® Community?
Firewise USA® is a national wildfire-preparedness program run by the National Fire Protection Association, or NFPA.
In the Tahoe Basin, the program is coordinated by the Tahoe Resource Conservation District with support from local fire agencies, including the North Lake Tahoe Fire Protection District and Tahoe Douglas Fire Protection District.
Recognition is based on organized neighborhood participation and continued wildfire-risk-reduction work.
Resident Organization
A neighborhood forms a resident committee to help organize and document wildfire-preparedness efforts within the community.
Risk Assessment
Participating communities complete a wildfire risk assessment to identify vegetation, access, fuels, and other local risk factors.
Ongoing Mitigation
Recognition requires continued work such as brush clearing, fuels reduction, and other wildfire-preparedness activities rather than a one-time certification.
Annual Renewal
Firewise status is renewed annually, so buyers should verify the current recognition status of the specific neighborhood rather than assuming a community's prior designation is still active.
Do Not Assume Every East Shore Neighborhood Has the Same Status
Incline Village, Cave Rock, Skyland, Zephyr Heights, Round Hill, Glenbrook, and other East Shore areas are actively involved in wildfire-risk-reduction work, but current Firewise USA recognition can vary by neighborhood and year.
Verify the specific community's current status before relying on it for insurance or property-buying decisions.
Calculate Your Potential Nevada Tax Savings
If Nevada's tax structure is one of the reasons you are considering a Tahoe move, estimate the potential tax difference while also accounting for insurance, wildfire mitigation, property taxes, and other carrying costs.
Use the NV Tax Savings Calculator
Does Firewise Status Actually Lower Your Insurance Premium?
Sometimes, but not automatically.
A recognized Firewise community can be a positive underwriting factor, but discounts depend on the insurance carrier, policy, property, and current eligibility rules.
Community status should therefore be treated as one piece of the insurance picture rather than a guaranteed discount.
Some Carriers Offer a Firewise Discount
The source identifies USAA as a documented example, with a discount typically around 5% for eligible policyholders in recognized Firewise communities. Eligibility and availability should be confirmed directly with the carrier.
The House Itself Can Matter More
A Class A fire-rated roof, ember-resistant vents, defensible space, vegetation management, and other home-specific mitigation can be important factors in underwriting and may matter more than the neighborhood designation alone.
Compare Coverage, Not Just the Premium
A lower insurance quote is not necessarily a better policy. Confirm what is actually covered, what is excluded, the deductible, and whether wildfire loss is included before comparing the final cost.
Important: Verify Wildfire Coverage in Writing
The source notes that Nevada changed its insurance rules in 2024 to allow policies that can exclude wildfire coverage in exchange for a lower premium.
That makes it especially important to compare the actual policy language rather than assuming two homeowners-insurance quotes provide equivalent protection.
Before removing loan or insurance contingencies, ask the insurance professional to confirm in writing whether wildfire damage is covered.
Planning to Make Nevada Your Primary Residence?
Insurance is only one part of a California-to-Nevada, Washington-to-Nevada, or other high-tax-state relocation. Use The 2026 NV Residency Guide to understand the broader practical transition.
Explore The 2026 NV Residency GuideWhy Home-Level Wildfire Mitigation Still Matters
Firewise recognition focuses on neighborhood-level organization and mitigation, but insurers still evaluate the individual property.
That means a home inside a well-organized wildfire-prepared community can still have insurance challenges if the structure or surrounding landscaping has significant vulnerabilities.
Roof
Determine whether the home has a Class A fire-rated roofing system and whether the roof condition creates any obvious wildfire or underwriting concerns.
Vents
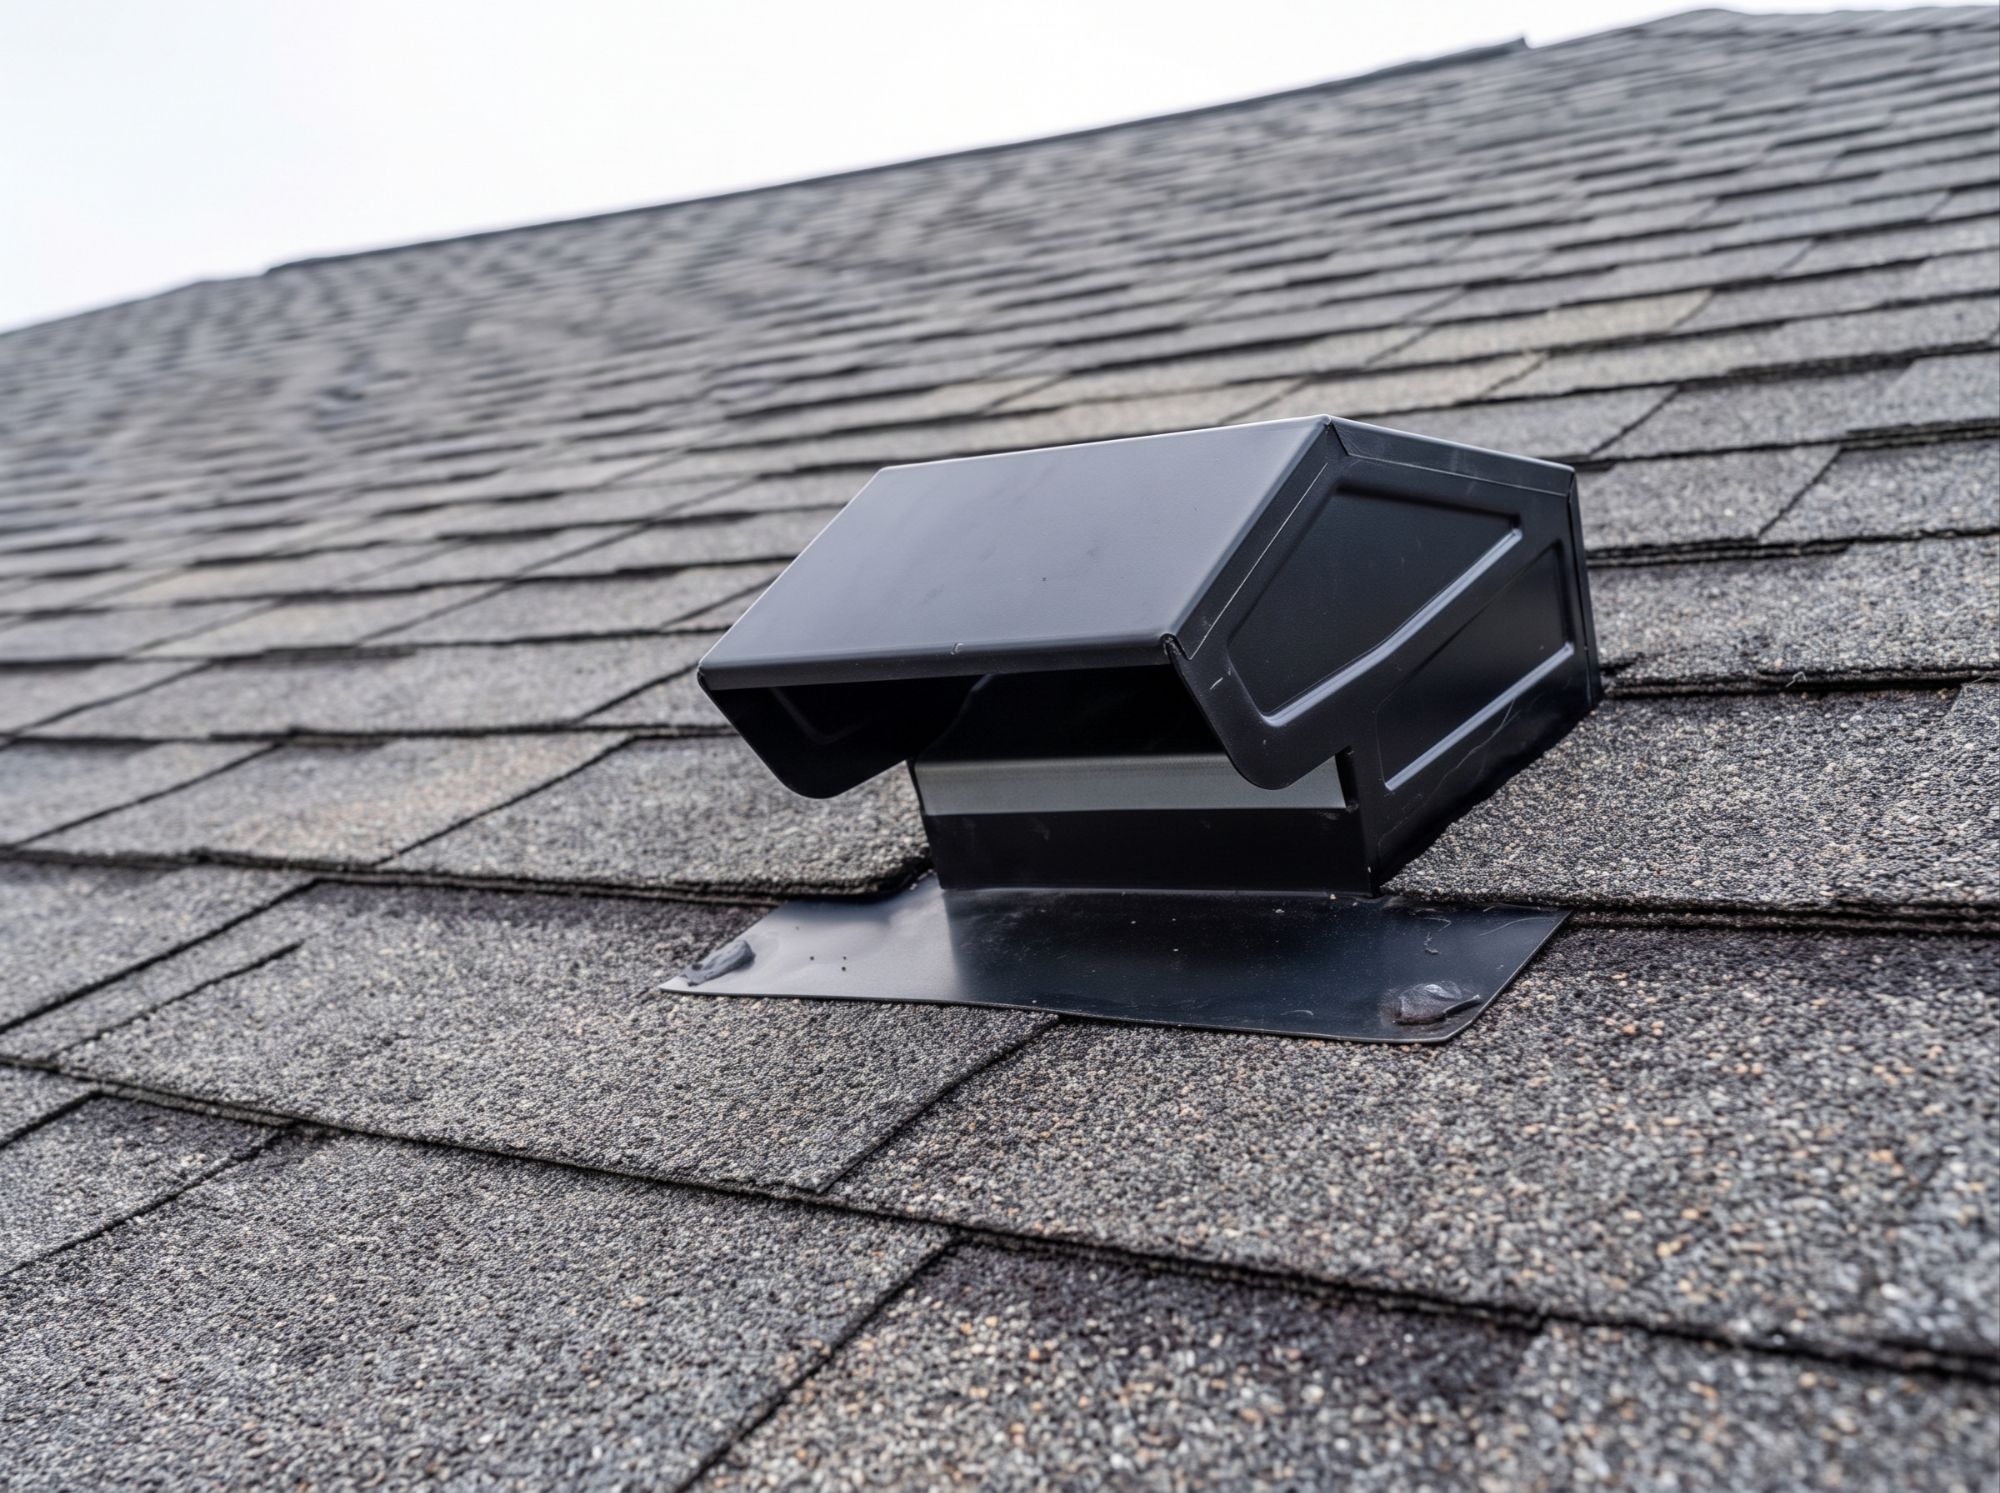
Ember-resistant vents can help reduce the opportunity for wind-driven embers to enter attic and crawl spaces.
Defensible Space
Review vegetation, pine needles, brush, wood piles, and other combustible materials immediately around the structure.
Documentation
Ask whether the property has recent defensible-space evaluations or other wildfire-mitigation documentation that may help an insurance professional understand the home's condition.
What Is Required to Keep Firewise Recognition?
Firewise recognition is not permanent. Participating communities need to continue documenting wildfire-risk-reduction efforts.
The source explains that communities generally invest the equivalent of approximately one volunteer hour per dwelling unit each year in wildfire-preparedness work.
In HOA communities, much of that coordination may be organized at the neighborhood level. The important point for buyers is that Firewise status reflects continued participation rather than a one-time award.
Firewise Recognition Is Helpful Context, Not a Substitute for Due Diligence
A current Firewise designation can indicate that a neighborhood takes wildfire preparedness seriously, but it does not guarantee that an individual property will be inexpensive to insure or that every insurance company will offer the same terms.
Before You Write an Offer: A Quick Insurance & Firewise Checklist
Insurance should be investigated early in the purchase process rather than treated as a final administrative step just before closing.
What Nevada Tahoe Buyers Should Verify
- Confirm whether the specific neighborhood currently holds Firewise USA recognition.
- Ask the insurance carrier whether Firewise status changes the quote or qualifies for any discount.
- Verify whether wildfire damage is included or excluded from the policy.
- Review the roof, vents, defensible space, and vegetation condition of the individual home.
- Ask for an insurance quote before loan and insurance contingencies expire.
- Compare deductibles, exclusions, coverage limits, and actual policy terms, not just the annual premium.
Build a More Deliberate Nevada Transition
If your Tahoe property will become part of your Nevada residency strategy, use the NV Residency Guide - Safe Harbor Checklist to organize practical documentation and relocation steps alongside the real estate purchase.
Get the Safe Harbor Checklist
The Bottom Line
Nevada's lack of an individual state income tax, favorable property-tax environment, and communities that actively invest in wildfire preparedness can make the Nevada side of Lake Tahoe attractive to relocating buyers.
But the smartest comparison looks beyond taxes and the headline insurance premium.
Verify the neighborhood's current wildfire-preparedness status, obtain a property-specific insurance quote, understand the individual home's mitigation condition, and confirm exactly what the policy covers before your contingencies expire.
Buying on the Nevada Side of Lake Tahoe?
Tahoe Tony has spent more than 28 years helping buyers navigate homes in Incline Village, Glenbrook, Zephyr Cove, and the Nevada side of Lake Tahoe.
He can help you investigate a neighborhood's current wildfire preparedness, review property-specific considerations, and connect you with local insurance professionals who can provide a real carrier-specific picture before you are locked into a purchase.
Schedule a Property Insurance & Firewise ReviewThis article is for general informational purposes only and does not constitute insurance, legal, tax, financial, wildfire-safety, underwriting, Firewise, NFPA, or real estate advice. Firewise USA recognition, community participation, carrier eligibility, discounts, premiums, wildfire exclusions, deductibles, insurance availability, defensible-space requirements, underwriting standards, and state laws can change. Recognition status can vary by neighborhood and year. Buyers should independently confirm current Firewise status with the appropriate program or local agency and obtain property-specific insurance information directly from a licensed insurance professional before removing contingencies. Tony Tuoto is a licensed real estate broker, not an insurance agent, CPA, tax attorney, NFPA representative, or fire official.
Nevada Tahoe Firewise & Insurance FAQ
Frequently Asked Questions
Common questions Nevada Tahoe buyers ask about Firewise USA communities, wildfire mitigation, insurance discounts, coverage, and property-specific due diligence.
What is a Firewise USA community? +
Firewise USA is a national wildfire-preparedness program run by the National Fire Protection Association. Participating communities organize residents, complete a wildfire-risk assessment, and maintain ongoing mitigation efforts such as fuels reduction and brush clearing.
Who coordinates Firewise USA in the Tahoe Basin? +
The source identifies the Tahoe Resource Conservation District as the Firewise USA regional coordinator for the Tahoe Basin, working with supporting local fire agencies including the North Lake Tahoe Fire Protection District and Tahoe Douglas Fire Protection District.
Does living in a Firewise community lower Nevada Tahoe home insurance? +
Sometimes. Discounts are carrier-specific and are not guaranteed. The source identifies USAA as a documented example with a discount typically around 5% for eligible policyholders in recognized communities, while other carriers may treat Firewise status differently.
Is Firewise status more important than the condition of the home? +
Not necessarily. Home-specific features such as a Class A fire-rated roof, ember-resistant vents, defensible space, and vegetation management can be very important to an insurance carrier's evaluation of the property.
Can a Nevada homeowners policy exclude wildfire coverage? +
The source notes that Nevada changed its rules in 2024 to permit policies that can exclude wildfire coverage in exchange for a lower premium. Buyers should confirm the actual current policy terms with a licensed Nevada insurance professional and verify wildfire coverage in writing before comparing quotes.
Which Nevada Tahoe neighborhoods participate in wildfire mitigation? +
The source identifies areas such as Incline Village, Cave Rock, Skyland, Zephyr Heights, Round Hill, and Glenbrook as communities where wildfire-risk-reduction work is active. Firewise USA recognition can change annually, so current neighborhood status should be verified rather than assumed.
Is Firewise USA recognition permanent? +
No. Firewise recognition is renewed annually. Participating communities continue reporting mitigation work and maintaining the program requirements to keep recognition current.
What should I check before comparing Nevada Tahoe insurance quotes? +
Compare whether wildfire damage is covered, deductibles, exclusions, policy limits, home-level wildfire mitigation, any Firewise-related discount, and the actual annual premium. Do not compare price alone.
What should I verify before buying a home in a wildfire-prone Tahoe neighborhood? +
Verify the neighborhood's current Firewise status, obtain a property-specific insurance quote, review the roof, vents and defensible space, confirm wildfire coverage, and understand any mitigation requirements before removing contingencies.
If your purchase is also part of a Nevada relocation, review the 2026 NV Residency Guide and the Safe Harbor Checklist .
Categories
Recent Posts